
Ben Nash. Last reviewed November 2026.
This is general information for Australians. It’s not personal financial, tax, or legal advice. Consider getting advice from a licensed financial adviser and a registered tax agent before acting.
Paying down your mortgage, or holding cash in an offset account (an account linked to your home loan that reduces the balance you’re charged interest on), gives you a return equal to your home loan rate with no market risk, and the interest you save isn’t taxed. At 6.21%, the Reserve Bank’s average rate on owner-occupier home loans in August 2026, someone on the top rate of 47% would need a savings account paying about 11.7% before tax to match it. Shares can beat your home loan rate after tax and fees over long periods, mainly because their growth isn’t taxed until you sell, but they won’t do it every year. So for most people the answer ends up being an order of moves, starting with a cash buffer in the offset and then using super and investing for whatever’s left over.
- Every dollar in your offset saves interest at your home loan rate, with no market risk for as long as the loan is there, though the saving moves up and down with your rate
- Australian shares returned 9.0% a year before fees and tax over the 30 years to 30 June 2026, but part of that return is taxed each year and none of it is guaranteed
- Growth on shares isn’t taxed until you sell. For growth from 1 July 2027 on shares held at least 12 months, the 50% discount (tax on only half the gain) is replaced by taxing the gain above inflation at your marginal rate with a 30% minimum, and growth up to then keeps the discount
- For high earners, before-tax super contributions (concessional contributions) can come out ahead of both the offset and investing in your own name on tax, as long as you’re comfortable with the money being locked away until retirement
- Consider giving the money in your offset a reason and a review date, because leaving it there by default is one of the most common and most expensive mistakes I see
Is paying off your mortgage really a risk-free return?
Yes, for as long as you have the loan. Money in an offset account is subtracted from your loan balance before the bank works out the interest, so a $500,000 loan with $20,000 in the offset is only charged interest on $480,000 (Moneysmart explains how offset accounts work). An extra repayment does the same job on the loan itself. Either way, every dollar saves interest at your home loan rate, and the saving doesn’t depend on what markets do.
The saving also isn’t taxed, because interest you never pay the bank never shows up in your tax return. If you had the same money in a savings account, the interest would be added to your income and taxed at your marginal rate (the rate on your top dollars of income). So a savings account would need a much higher rate to leave you with the same amount, and the higher your income, the bigger that gap gets.
But there’s a ceiling on this return. An offset can never pay you more than your mortgage rate, and when interest rates fall, your return falls with them. The return also stops completely once the loan is paid off.
So cash in the offset does its best work when it’s there for a reason, like your emergency buffer or money you’ll need in the next few years. It ends up costing you the most when it’s sitting there because you never got around to deciding where it should go.
A couple we worked with a few years back had around $850,000 from an inheritance sitting in the offset account on their home loan. By the time we started chatting, the money had been there for three years. They’d always planned to get around to investing it, but life was busy, and they told me they actually enjoyed watching the interest on the mortgage shrink because it felt like the money was doing something.
When we built their plan, the couple decided to keep $100,000 in the offset as their emergency buffer and put $450,000 into a diversified index fund portfolio. They used the remaining $300,000 as the deposit and costs on an investment property. So the buffer stayed in the offset for a reason, and the rest of the money moved into assets that could grow. Looking back, their three years in the offset had lined up with strong years for both shares and property, so the default had cost them more than the long-run averages would suggest.
Earlier in my career, I’ll confess, I didn’t think holding money in an offset was a bad idea, because it was safe and flexible and it saved real interest. It was only after running the numbers on this decision hundreds of times with real clients that I saw how much leaving money there by default can cost.
What happens to $100,000 if it sits in the offset or goes into shares for 20 years?
Over a long stretch, a growth investment can leave you well ahead of the offset, even after tax, because most of its return isn’t taxed until you sell. Income from the investment, like dividends, is taxed every year at your marginal rate. But growth isn’t taxed until you sell. And for growth from 1 July 2027, on investments held at least 12 months, what you paid for the investment (the cost base) is indexed to inflation. Only the gain above inflation is taxed, at your marginal rate with a 30% minimum.
Both paths start with the same $100,000, on these assumptions.
- You’re on the top rate of 47% (the 45% bracket plus the 2% Medicare levy) for all 20 years, including the year you sell
- The home loan rate stays at 6.21%, the Reserve Bank’s average for owner-occupier loans in August 2026, and the loan stays big enough to offset the whole amount for 20 years
- US shares return an assumed 10% a year before fees, made up of 8% growth and 2% income, and the income left after tax is reinvested. That’s higher than the 9.0% a year Australian shares returned over the 30 years to 30 June 2026, which is the figure the rest of this post uses
- The money goes in on 1 July 2027, so all of the growth falls under the new capital gains tax rules
-
Inflation runs at 3% a year, the top of the Reserve Bank’s 2% to 3% target, and that’s the rate the cost base is indexed by
-
Path A keeps the $100,000 in the offset. The interest it saves each year stays against the loan too, so the money compounds at 6.21% with no tax. After 20 years it adds up to $333,663, made up of the $100,000 still in the offset and $233,663 less owing on the loan
- Path B puts the $100,000 into US shares. Each year the shares grow 8% and pay 2% as income, and on the top rate, 47% of that income goes in tax, so 1.06% is left to reinvest and the portfolio grows about 9.06% a year
- Over the 20 years the income adds up to $103,012, of which $48,416 goes in tax and $54,596 is reinvested. Before any sale, the portfolio is worth $566,643
- When you sell, the cost base is the original $100,000 plus the $54,596 reinvested, which comes to $154,596. Indexed to inflation from the date each amount went in, it becomes $248,135, which leaves a gain above inflation of $318,509
- That gain is taxed at the top rate, so the capital gains tax is $149,699, and the 30% minimum doesn’t come into it because the top rate is higher. After that tax, path B leaves you with $416,944
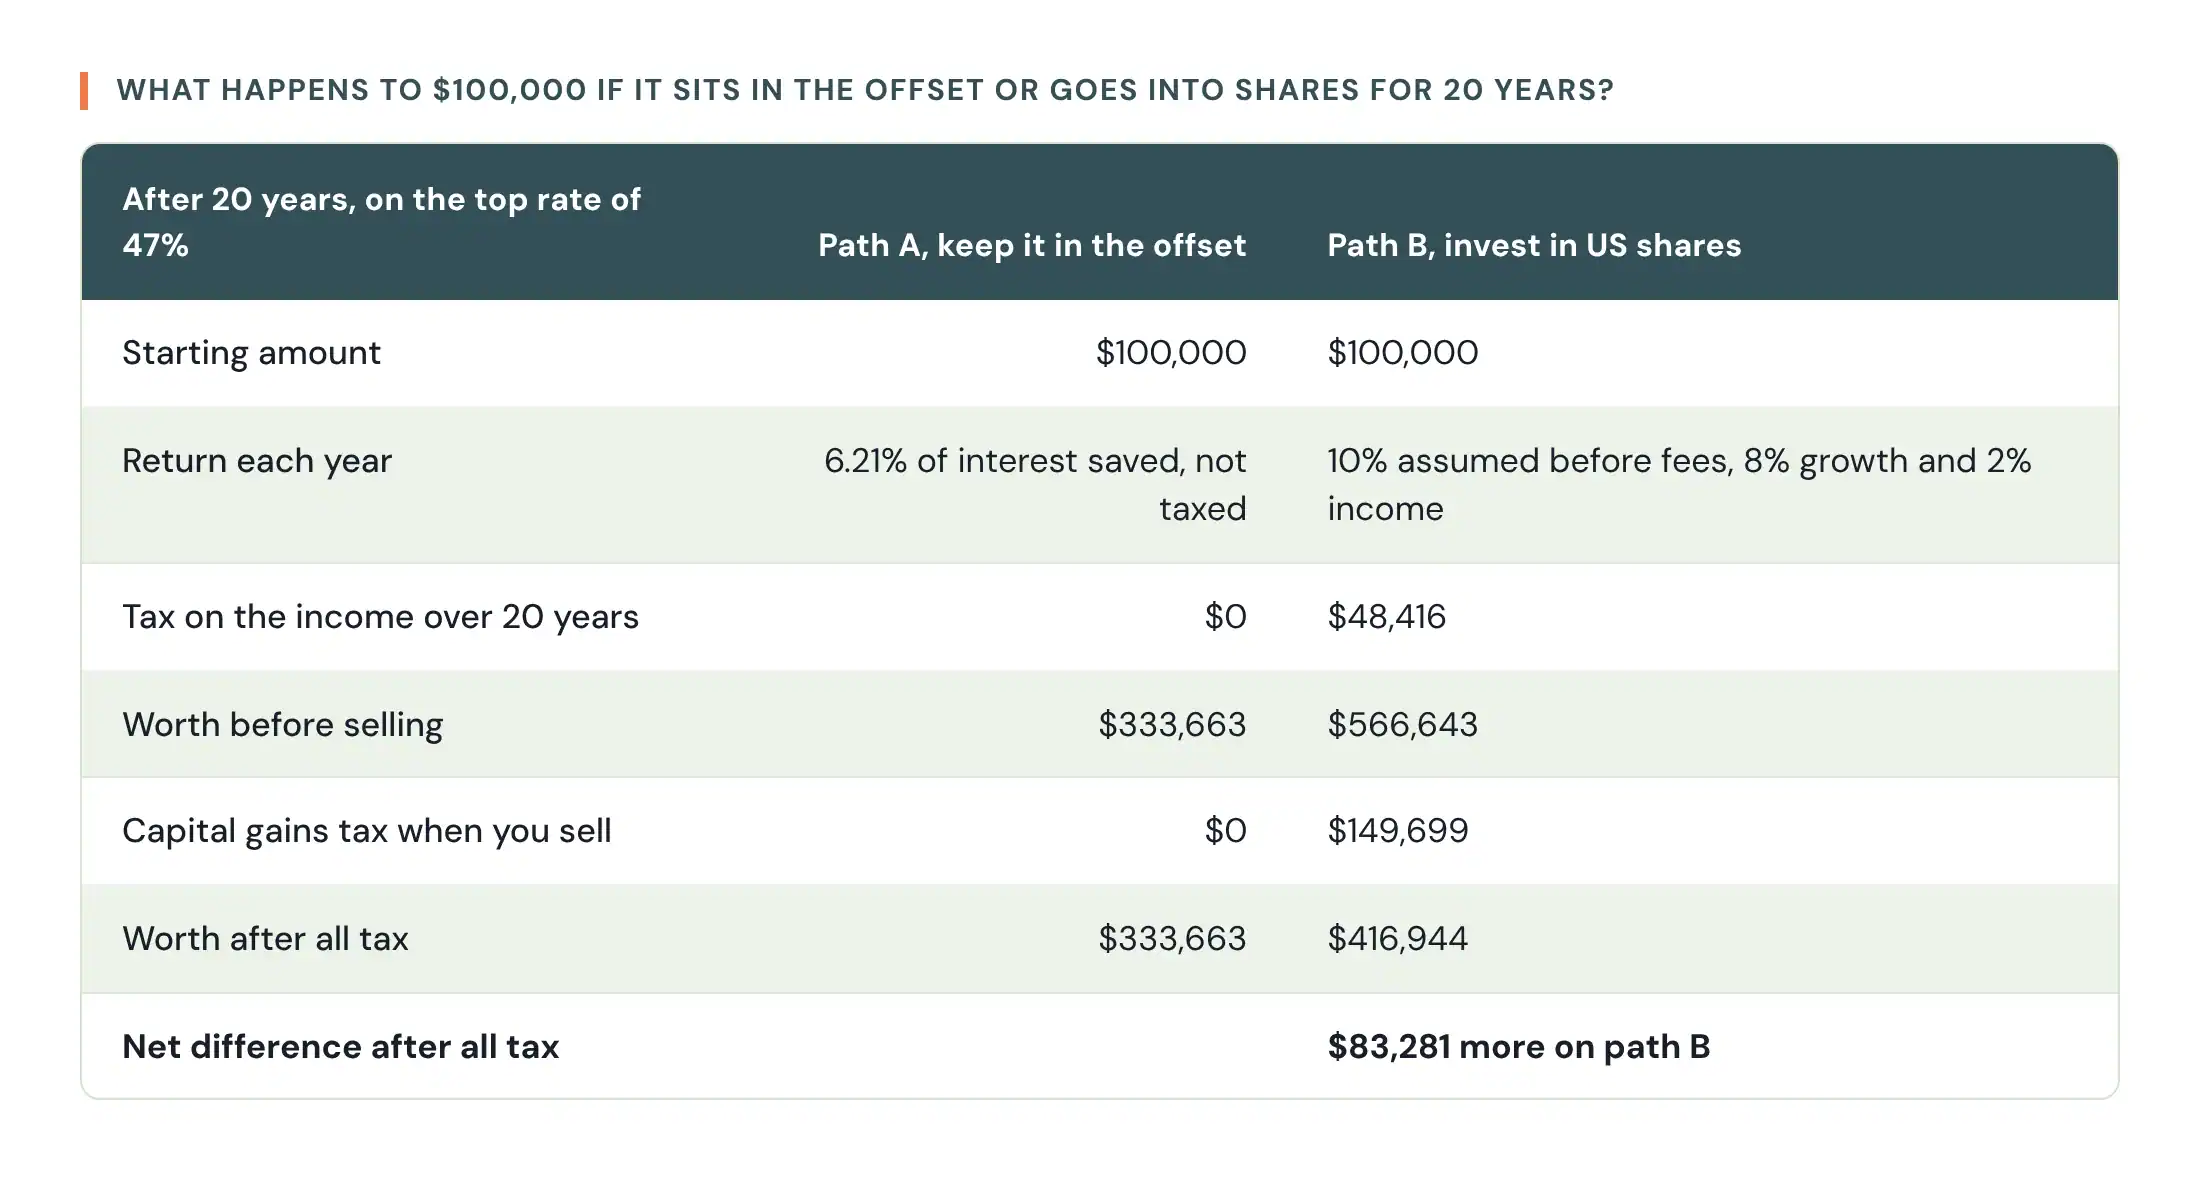
On these assumptions, path B finishes $83,281 ahead of the offset once every dollar of tax is paid, before any fees. Before you sell, path B is $232,980 ahead. But $149,699 of that is tax you’ll still owe when you sell, so the after-tax figure is the fair one to compare.
So it pays to be selective about what you invest in, because the result depends on how the return arrives. Investments that pay a low income and get most of their return from growth are what make this work for a high earner. The growth compounds without tax until you sell, while the yearly tax only touches the 2% income. And on the top rate, a shift in that mix, or in the return itself, can move the answer a lot.
- If the same 10% came as 5% income and 5% growth, path B would end at $385,010 after all tax, and the gap over the offset would narrow to $51,347
- If the whole 10% came as income taxed every year, like interest from a cash or bond fund, path B would end at $280,910, which is $52,753 behind the offset
- With 2% income but only 7% growth, so 9% in total, path B would end at $363,298 after all tax, just $29,635 ahead
- With a fee of 0.2% a year, around what a low-cost index fund charges, coming off the 10% return, path B would end at $405,466 after all tax, $71,803 ahead
- With a fee of 0.5% a year, path B would end at $388,970, and the gap would narrow to $55,307
And 10% is an assumption for this example, not a forecast. Returns aren’t guaranteed, shares can fall sharply in any single year, and with US shares the Australian dollar moves your return up or down as well.
What are the most common mistakes when you’re deciding to pay off the mortgage or invest?
Most of the expensive mistakes here come from treating the decision as a one-off choice rather than part of a plan you revisit.
The first is leaving money in the offset by default. For some people the offset is exactly the right home for their cash, like when your income is patchy, your job feels a bit shaky or you haven’t built an emergency buffer yet.
The problem comes when the money’s sitting there because nobody made a decision, like it was for the couple above. The offset never sends you a statement showing the growth you missed. People who get this right give the offset money a reason and a review date, usually at a set point each year.
The second is investing before you’ve got a buffer. Without cash set aside, a lost job or a big bill during a market fall can force you to sell shares at the wrong time and lock in a loss you’d otherwise have waited out. A common starting point is three months of core living costs held in the offset, where it’s still saving interest. Business owners and anyone on variable income usually hold more.
The third is comparing the pre-tax share return with your mortgage rate. A 9.0% long-run return against a 6.21% home loan rate looks like a pretty easy win. But the share return is before fees and tax, and the mortgage saving is after both.
The fair comparison is after tax, at your own tax rate and for the way the investments are owned. This is one of the places an adviser can change the outcome, by modelling whose name the investments should sit in and how much should go through super first.
The fourth is paying extra into the home loan and then redrawing it to invest or to buy a car. The interest on redrawn money generally follows what the money was used for, so mixing purposes inside one loan can leave you with a split that’s messy to work out at tax time. Holding the cash in an offset keeps it separate from the loan in the first place.
The fifth is ripping up the plan every time rates move. The Reserve Bank has raised rates five times in 2026, and it’s really tempting to change course with each one. It usually works better to set your split in a plan and review it once a year, or sooner when something big changes, like a new job or a large bonus.
How much does an investment need to earn to beat your mortgage?
To beat the offset, an investment has to earn more than your home loan rate after tax and fees. The quickest way to see where that bar sits is to gross your mortgage rate up for tax. You do that by dividing it by one minus your marginal rate, with the 2% Medicare levy included.
The Reserve Bank’s average rate on outstanding owner-occupier home loans was 6.21% in August 2026, with variable and fixed loans combined. That average is from before the cash rate rose twice more, to 4.85% on 3 November 2026. So most variable home loan rates are higher now, and it’s worth running the same sum on your own rate. Using 6.21% and the 2026-27 resident tax rates, these are the pre-tax returns a fully taxed investment would need to match the offset.
- On the top rate of 47%, for income over $190,000, 6.21% ÷ 0.53 = about 11.7%
- On 39%, for income from $135,001 to $190,000, 6.21% ÷ 0.61 = about 10.2%
- On 32%, for income from $45,001 to $135,000, 6.21% ÷ 0.68 = about 9.1%
Nothing low risk pays rates like that. Australian shares have returned 9.0% a year over the 30 years to 30 June 2026, before fees and tax, based on the S&P/ASX total return figures in Vanguard’s 2026 Index Chart. That’s a long-run average, and some of the years inside it were negative.
Shares don’t need to clear those numbers in full, though, because not all of the return is taxed each year. Dividends are taxed in the year you receive them, and franking credits (tax the company has already paid) reduce that bill. Growth isn’t taxed until you sell, so it keeps compounding on the full amount in the meantime. The table below shows both ends of that range for the next $100,000 in its first year, on the top rate.
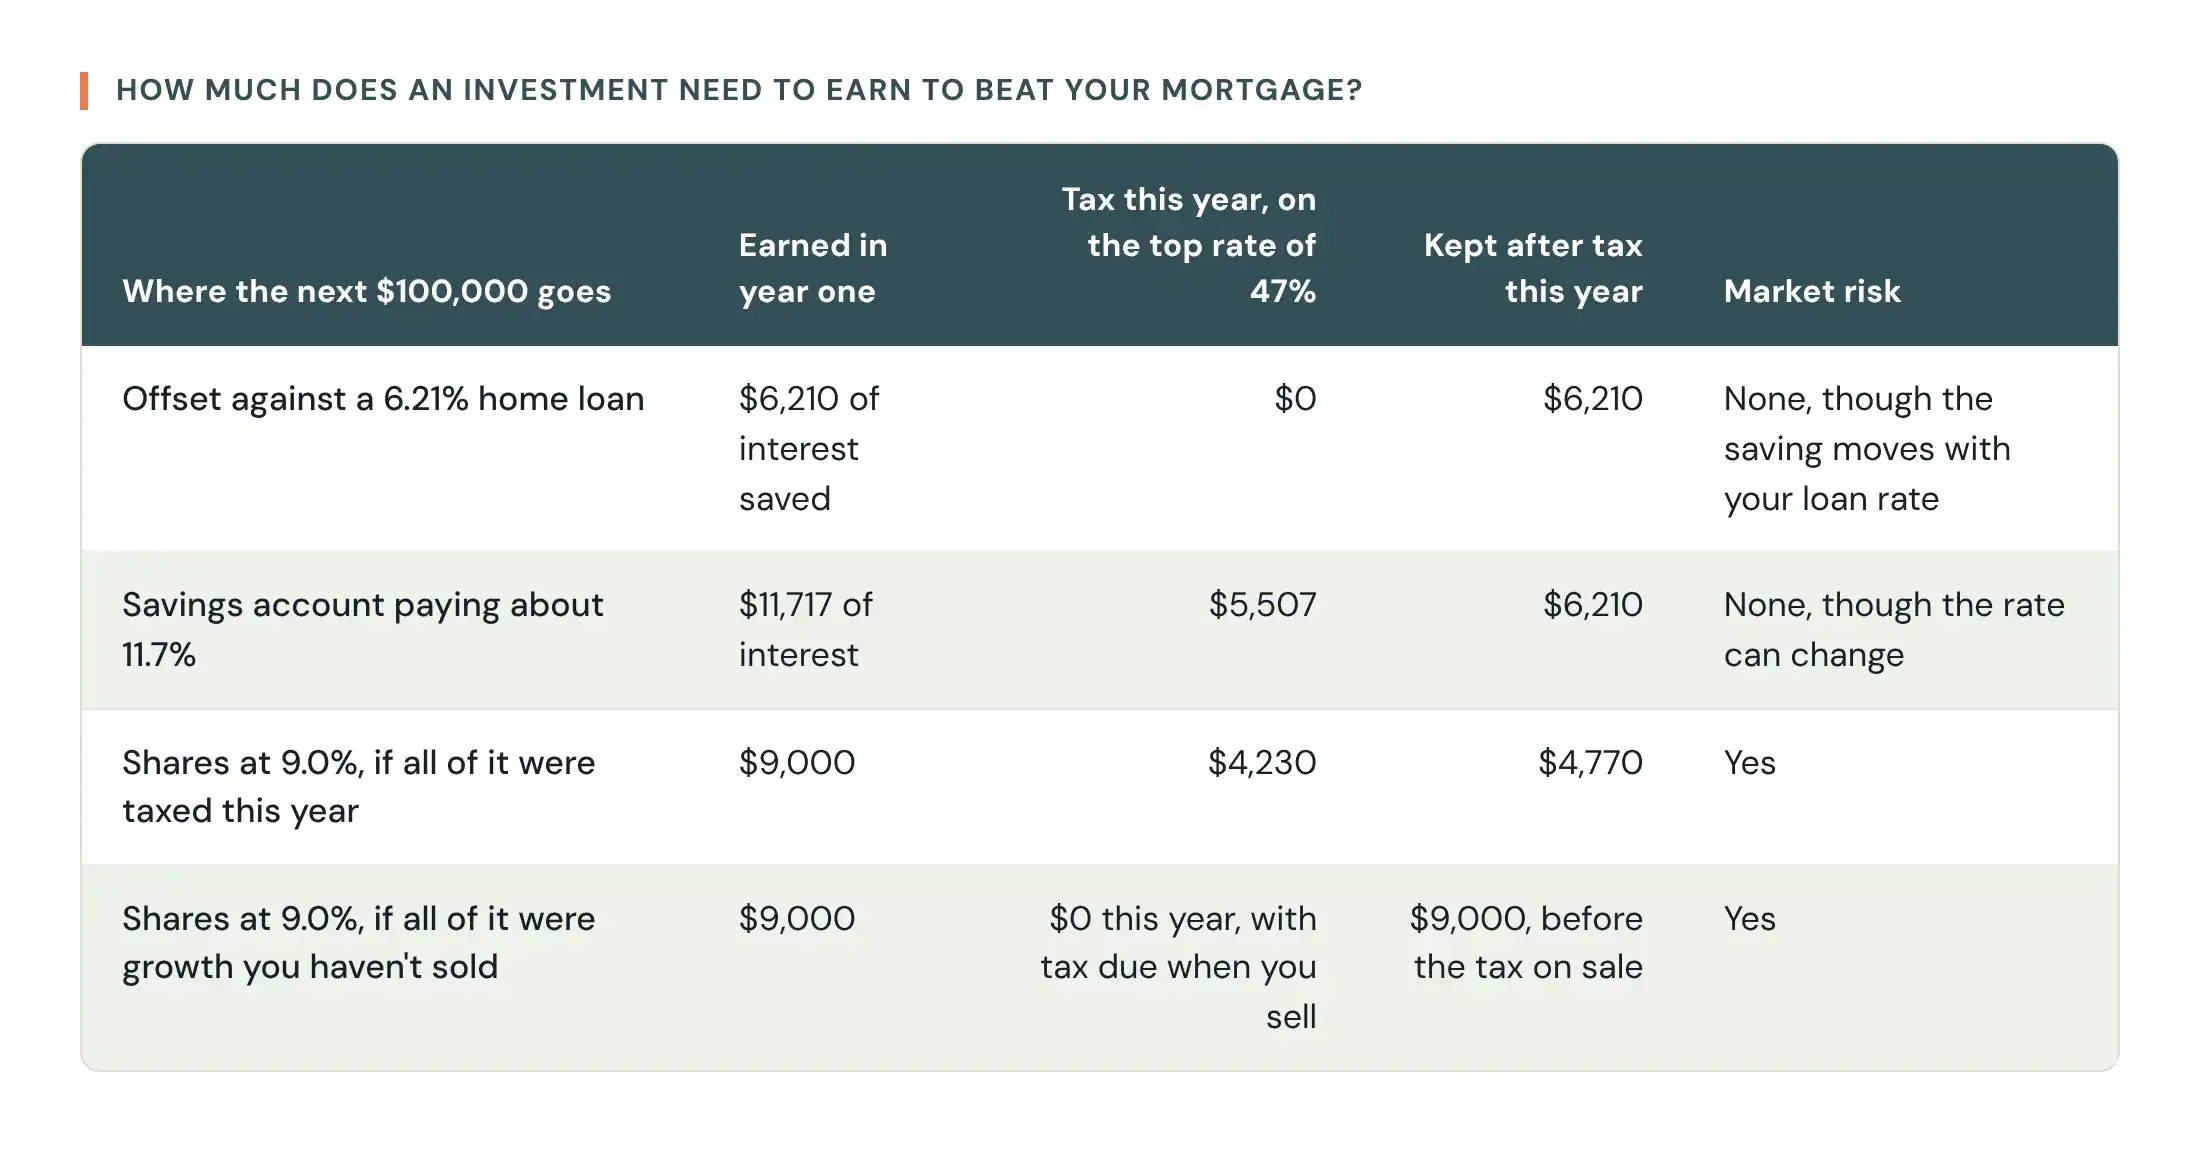
On the top rate, the offset keeps all $6,210 it saves in year one, and the savings account ends up with the same amount once its tax bill is paid. Shares leave you with somewhere between $4,770 and $9,000 that year, before any tax on sale.
A real share portfolio lands somewhere between those last two rows, depending on how much of the return arrives as dividends and how much franking comes with them. Fees come off as well. So in a single year on the top rate, shares sit pretty close to the offset rather than miles ahead of it. And in a year when markets fall, the offset wins easily.
The case for investing comes from time and structure, as the 20-year example earlier shows. The growth is taxed later, an investment portfolio keeps paying you after the mortgage is gone, and that income is what eventually lets work become optional. The offset’s return ends with the loan, and it falls with every rate cut. Working out where your own portfolio would land between those rows, for your tax rate and the way it’s owned, is a big part of what we model when we build a plan.
How does the 1 July 2027 capital gains tax change affect your decision?
Your home isn’t affected. The rule that your own home is free of capital gains tax (the main residence exemption) hasn’t changed. So paying down your own home loan carries no capital gains tax either way, and the change only lands on the investing side of the decision.
Under the rules that apply until 30 June 2027, an individual who has held shares for at least 12 months pays tax on half the capital gain (the 50% discount). Two Acts that became law on 26 June 2026 (Acts 49 and 50 of 2026) change that for growth from 1 July 2027. For that growth, on shares held at least 12 months, the discount is replaced by indexing what you paid (the cost base) to inflation. The gain above inflation is then taxed at your marginal rate, with a minimum rate of 30%, as the ATO’s page on the capital gains tax reform sets out.
Growth up to 30 June 2027 keeps the 50% discount. For shares you already own, the gain is split using their market value just before 1 July 2027, and the tax is still only paid when you actually sell. The ATO says the government is still developing an alternative way of splitting the gain (an apportionment method), so that part isn’t law yet.
For someone on the top rate of 47% who holds shares for many years, half the gain is taxed under the current rules, so the effective rate on the whole gain is 23.5%. Under the new rules, the part of the gain above inflation is taxed at their full marginal rate, so whether they pay more or less than before depends on how much of the growth was inflation. On the top rate, they only come out ahead of the old rules when inflation makes up more than half the growth. And for anyone selling in a low-income year, like early retirement, the minimum stops the rate on the real gain dropping below 30%, unless they get a listed income support payment like the age pension that year. Our explainer on how the 1 July 2027 capital gains tax change works covers the valuation step and who comes out ahead.
If the investment you have in mind is a property, the negative gearing changes from the 12 May 2026 Budget matter as well, and they’re now law under Schedule 2 of Act 49 of 2026. From 1 July 2027, losses on established residential property bought after 7.30pm AEST on 12 May 2026 can no longer reduce the tax on your wages. They can still be used against other residential rental income and gains, or carried forward.
Is it better to keep money in your offset or pay off the mortgage?
For the interest you save, the two are the same. A dollar in the offset and a dollar paid off the loan both cut your interest at the home loan rate.
The difference is access. Money in the offset stays yours to take out at any time. Extra repayments become part of the loan, and getting them back means a redraw, which some lenders limit and which brings the loan purpose problem from the mistakes above.
The catch is that some offset accounts come with a higher rate or a package fee, so it’s worth checking yours against a basic loan every couple of years, which a mortgage broker can do for you. Our guide to how an offset account works goes through how much to keep there and how to set it up.
What’s the best order for paying off the mortgage and investing?
For most high earners, the order I see work looks something like this. It’s a starting point you can shape to your own situation, rather than a rule.
- Build a cash buffer in the offset, sized to your income and the risks you’re carrying
- Clear any credit card or personal loan debt, which usually costs far more than your mortgage
- Consider using your concessional super cap if you won’t need the money before retirement
- Split your ongoing surplus between the offset and investing, with the investing share set in your plan
- Consider debt recycling (turning home loan debt into tax-deductible investment debt over time) once the buffer is in place and you’re investing anyway
- Review the split once a year, and after any big change to your income or family
For high earners, the third step is often the biggest lever. Concessional contributions, which include your employer’s contributions and any salary sacrifice (salary your employer pays into super before tax), count towards the $32,500 concessional cap for 2026-27. They’re generally taxed at 15% in the fund rather than at your marginal rate. The extra contributions are usually made through salary sacrifice with your employer, or as a personal contribution you claim as a tax deduction once your fund has acknowledged your notice of intent (a form telling the fund you’ll claim the deduction). It’s worth checking how much room is left under the cap each year before the financial year ends, which you can do through ATO online services in myGov.
Where your income plus super contributions is over $250,000, Division 293 adds another 15% on the lesser of your concessional contributions and the amount you’re over the threshold. So on the top rate, $1,000 of salary ends up as one of these amounts, depending on where it goes.
- $530 in your hand to put in the offset
- $850 in super, after the 15% contributions tax
- $700 in super, where Division 293 applies to it
But the money in super is locked away until you meet a condition of release, which for most people means retirement. So super suits money you won’t need before then.
How much of the surplus goes to investing depends on how long until you need the money and how steady your income is. Money you’ll need in the next two or three years, like school fees or a move, usually sits better in the offset than in shares. It also depends on how much of your wealth already sits in one place, like your home or your employer’s shares. Someone holding a lot of vested shares from their employer, known as restricted stock units (RSUs), might lean harder on the offset for a while, and someone with a long timeframe and secure income can lean more into investing.
Debt recycling is a way to turn your home loan into investment debt over time. The idea is that spare cash goes off the home loan and gets borrowed back on a separate split to invest, so the interest on that part can become tax deductible. It adds risk, because you’re investing with borrowed money, and it needs a clean set-up from day one, done with your lender and checked with a registered tax agent. Our guide to debt recycling in plain words covers how it works.
If you’d like to work through the order and split for your situation, you can book a 10-minute chat.
Do rising interest rates change the answer?
Rising rates raise the bar for investing. The Reserve Bank lifted the cash rate five times in 2026, taking it from 3.60% at the start of the year to 4.85% on 3 November 2026, and most variable home loan rates have moved up with it.
Each rise of 0.25% on a $500,000 loan adds $1,250 a year in interest. The same rise lifts the saving on every dollar in your offset by the same 0.25%, so the return an investment has to beat goes up with it.
Rates move the offset against shares comparison a lot more than they move the super comparison. The tax saving on a concessional super contribution comes from the gap between your marginal rate and the tax in the fund, and that gap doesn’t move when the Reserve Bank does.
Frequently asked questions
Should I put $100,000 on my mortgage or invest it?
At a 6.21% home loan rate, $100,000 in the offset saves about $6,210 a year with no tax and no market risk. So the answer really turns on whether your buffer’s in place and how long you can leave the money alone. If your buffer is sorted and the money won’t be needed for many years, a common approach is to check how much belongs in super first, then keep part in the offset and invest the rest.
Do you pay tax on the interest saved in an offset account?
No, the interest you save in an offset isn’t income, so it doesn’t go in your tax return. Interest earned in a savings account is different, because it’s added to your income and taxed at your marginal rate.
Is it better to put extra money into super or pay off the mortgage?
For high earners, super usually comes out ahead on tax, as long as you won’t need the money before retirement. Concessional contributions up to the $32,500 cap for 2026-27 are generally taxed at 15% in the fund, or 30% where Division 293 applies, against a marginal rate of up to 47% on the same dollars taken as salary. The mortgage wins on access, because super is locked away until you meet a condition of release.
Should I use my bonus or RSUs to pay down the mortgage?
The offset is a sensible place to hold a bonus or RSU proceeds while you decide, because it saves interest straight away and keeps the cash available. RSUs are generally taxed as income when they vest, so the tax is due whether you sell the shares or keep them. Our post on whether to sell RSUs when they vest covers that decision, and the proceeds then go through the same order as any other surplus.
Should I pay off my mortgage before I retire?
Most people aim to, because repayments are hard to fund once your salary stops. But that doesn’t have to mean extra repayments now at the expense of investing. A common approach is to build super and investments through your working years, then build up the offset as retirement gets closer and clear the loan around the time you stop work.
What if I have enough money to pay off my mortgage completely?
You can, but once the loan’s gone, the offset’s interest saving goes with it. Many people in this position keep the loan open and hold the money in a fully offset account instead, which saves the same interest and keeps the cash on hand. It also leaves room to decide how much to invest without having to borrow the money back first.
If you want some help with your money, we’ve created a free seven-day challenge you can use to get more out of your money you can join here and permanently level up your money in just seven days. And if you want to learn how financial advice can help you, you can schedule a quick call here.
Disclaimer: The information contained in this article is general in nature and does not take into account your personal objectives, financial situation or needs. Therefore, you should consider whether the information is appropriate to your circumstances before acting on it, and where appropriate, seek professional advice from a finance professional.